
Practical pet insurance decisions

Should we buy pet insurance?

Agree on what your household wants the policy to do before comparing prices or entering an application.

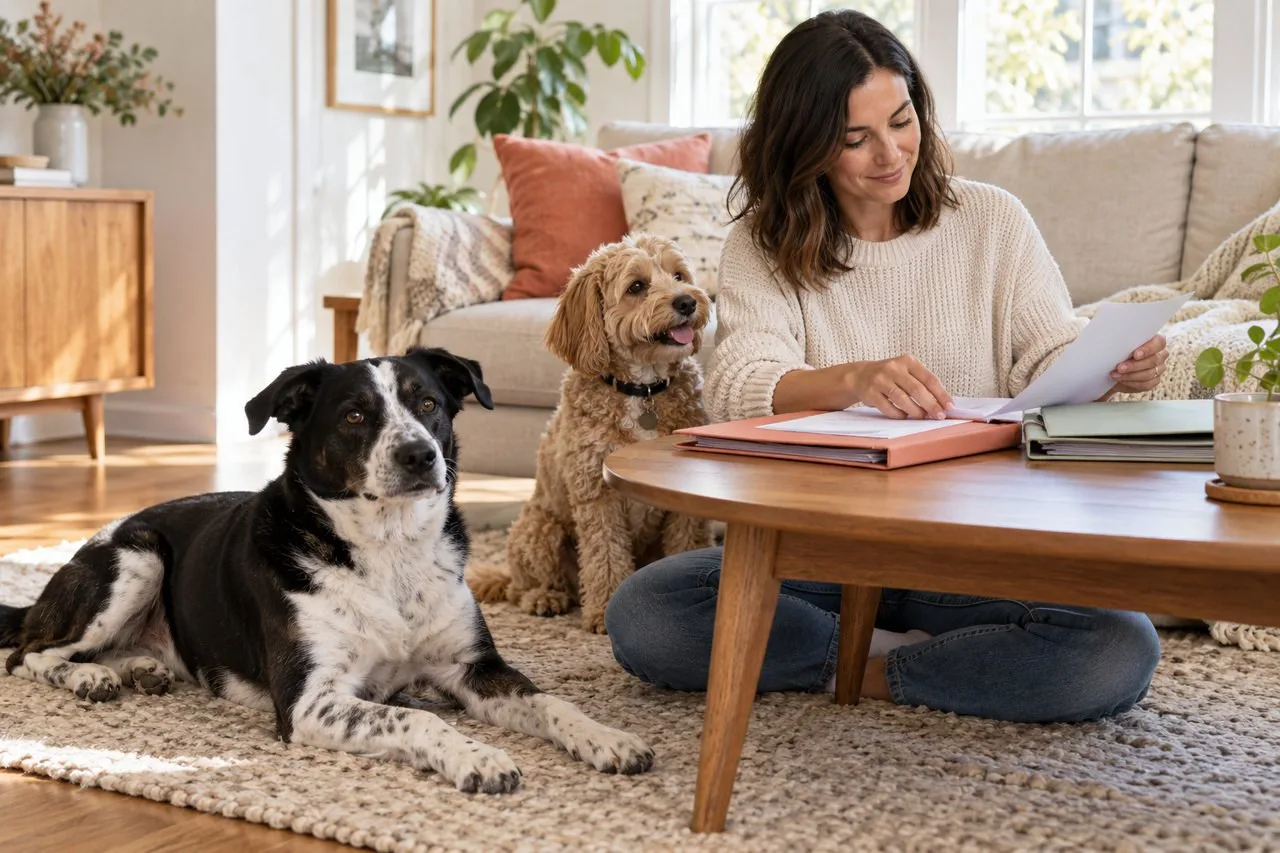
Owner organizing separate papers at home beside two dogs
✓ Policy-first ✓ Independent ✓ Useful checks
Direct answer
Buying pet insurance is worth considering when both the ongoing premium and the uncovered part of a major bill fit your household’s finances, and the policy protects against a risk you do not want to carry alone. If you can comfortably fund that risk yourselves, self-funding is also a real option. Make the decision together, including who pays the clinic, manages records and keeps the policy active.
What to know

Start with the disagreement, if there is one

One person may be asking whether insurance will save money. Another may be asking whether a large veterinary bill would force a difficult care decision. Those are different questions. Illinois insurance guidance warns that premiums can exceed benefits received. That does not settle whether transferring some uncertainty is useful to your household.

Each person should write down one concern without naming an insurer: an unaffordable operation, repeated treatment, unpredictable spending, or paying for a policy that may never reimburse anything. Compare the answers. A policy aimed at future unexpected illness will not necessarily solve a concern about routine examinations or a known problem already in the medical record.

Decision guide

Set three shared decisions before shopping

Decision Agree on this Do not leave this unresolved
Monthly commitment A premium you could continue paying alongside normal pet care. Which account pays and who checks renewal notices.
At the clinic How a deposit or full invoice would be funded before any reimbursement. Whether both people assume the other has the money available.
Uncovered care How to handle deductibles, excluded conditions and bills above limits. Treating insurance as permission to ignore the remaining exposure.

If you have more than one pet, keep the medical and coverage decisions separate even when you share a budget. One animal’s eligibility or available benefits do not establish another’s. A household discount, if offered, should be considered only after each proposed policy makes sense.

What to know

Use a hypothetical bill to uncover assumptions

Imagine an unexpected $4,000 clinic invoice. This is a planning exercise, not a typical treatment price. Ask who could pay it initially and what amount you would be comfortable retaining after a claim. Then ask an insurer to calculate its payment using your chosen deductible, reimbursement basis, exclusions and remaining limit. Do not simply multiply the whole invoice by an advertised percentage.

If the policy’s example leaves $1,200 with you, the useful question is whether you can fund that $1,200 plus premiums, while also bridging the larger clinic payment if required. If neither route is workable, a cheaper premium alone does not fix the cash problem. Revisit the benefit design and the care-funding plan before buying.

Compare

Gather the information once, then compare offers

  • Confirm the pet’s age or best documented estimate, species, breed description and home address.
  • Collect veterinary history, including previous practices, medications and earlier symptoms; do not wait for a new diagnosis to disclose relevant history.
  • Choose an initial coverage scope, deductible basis, reimbursement percentage and limit to compare. Note where products cannot be matched.
  • Ask about waiting provisions, excluded examination fees, ongoing-condition treatment at renewal and cancellation terms. Save written answers.
  • Decide whose name and contact details belong on the policy, and ask how another household member can communicate about it.

A quote is an offer to consider, not proof that a particular future claim qualifies. Finish reading the applicable documents before paying. If there is an existing policy, review the consequences of a switch before cancelling it; a new insurer can assess the history again.

What to know

Leave the conversation with a workable next step

If you agree to insure, choose the offer that fits the shared plan and record the effective date, relevant waiting-period end dates and first payment. Put the documents somewhere both decision-makers can find them. Make one person responsible for claims administration and name a backup.

If you choose to self-fund, specify the amount already available and the contribution you actually intend to make. Future savings are not money available for an emergency today. If you defer while clarifying a clause, identify the unanswered question and obtain a written response rather than allowing an unfinished comparison to become the default plan.

For a pet that is unwell now, arrange veterinary advice promptly. Deciding whether to buy future protection must not delay assessment or create an expectation that a new policy will pay for an existing episode.

Evidence

Sources and policy context

These public references support the consumer or veterinary context. Named insurer details were checked in official product materials; the policy offered for your pet and state determines the actual terms.

Next step

Compare Current Pet Insurance Rates

Check current options for your pet and location, then compare the policy details, exclusions, costs, and eligibility before choosing.

Compare the policy before you choose Check the actual offer, exclusions and out-of-pocket terms.
See Rate Options